Digital Pound Lab

An experimental platform for industry to test use cases and understand potential business models for a digital pound

The 12-month operational period of the Digital Pound Lab (the Lab) has now concluded. Across two phases, the Bank and participating organisations developed and demonstrated more than 30 use cases and payment journeys, showcasing how future payment capabilities could support a diverse range of experiences, from everyday retail payments and cash access through to trade finance, offline payments and emerging forms of digital commerce.

The outputs from both phases of the Lab, including videos of the use cases, can be found via the links below.

What is the Digital Pound Lab?

The Lab is an experimental platform which enabled hands-on experimentation for industry and the Bank. The Lab provided a simulated environment to test the potential capabilities of a digital pound, helping explore the feasibility of different use cases. It is not a regulatory sandbox and no real customers or real money payments are involved.

The goals of the Lab are:

  • co-creating use cases: collaborating with industry to test use cases that will contribute to the assessment of whether to build a digital pound;
  • understanding business models: collaborating with industry to understand potential business models for Payment Interface Providers (PIPs) and External Service Interface Providers (ESIPs);
  • supporting innovation: assessing the requirements for a digital pound to provide a platform for innovation; and
  • informing the Bank's emerging thinking: contributing to the Bank's emerging thinking on digital pound technology and digital currency technology more generally.

Some of the key lessons learnt during the Lab are discussed in the section below.
Phases of the Digital Pound Lab

The Lab ran from August 2025 to July 2026. There were two phases. Table 1, below, sets them out.

Table 1: Phases of the Lab

Phase

Purpose

Activities

Duration

Outputs

Phase 1

This phase tested a small number of use cases, aiming to understand whether and how a digital pound could improve existing payment services

See Annex 1 of the terms of participation for the list of use cases

Participants designed and built use cases which were defined by the Bank

Three months (August 2025 to November 2025)

See Phase 1 update for a summary of the outputs and videos of the use cases

Phase 2

This phase prioritised innovative use cases that demonstrate payment services that do not yet exist. However, use cases that demonstrate existing payments were also explored

Participants designed and built use cases that they defined

Nine months (November 2025 to July 2026)

See Phase 2 update for a summary of the outputs and videos of the use cases

Learnings from the Digital Pound Lab

The Lab brought together the Bank and industry participants to explore future payment capabilities through practical experimentation. Over two phases, more than 30 use cases and payment journeys were developed and demonstrated, including:

  • Everyday retail payments at point of sale, online and in-app. 
  • Cash access and cash deposit journeys, connecting digital pound services with existing ATM and cash infrastructure. 
  • Offline payments, including retail and transport scenarios. 
  • Public-sector payment services, such as recurring local-authority payments. 
  • Trade finance and business-to-business payments, including conditional and delivery-versus-payment arrangements. 
  • Delegated and programmable payments, including allowances, request-to-pay and conditional payments. 
  • Collaborative and embedded payments, including payments initiated within third-party applications. 
  • Identity-enabled payment services, using verifiable credentials and digital-verification services. 
  • Digital-asset and smart-contract interoperability. 
  • Emerging AI-assisted and agentic-payment journeys.

This helped validate the Lab’s hypothesis that many different payment experiences could be supported by a relatively small set of reusable capabilities, including aliases, conditional payments, verifiable credentials and common standards. Participants combined these capabilities in different ways to address a wide range of challenges and opportunities. A key insight from the Lab was that innovation often comes not from individual capabilities in isolation, but from how those capabilities are combined to meet user needs.

The Bank will continue to reflect on the evidence generated through both phases of the Lab. The findings have relevance not only to work on a potential digital pound, but also to wider work on the future of retail payments. The Lab has provided practical insight into the capabilities future payment systems may need, how they could work together, and where further experimentation may be valuable. 

Looking ahead, the Bank will continue to consider how practical experimentation can support its work on a potential digital pound and the future of retail payments, including exploring emerging payment capabilities and user needs. Areas of interest may include how delegation, permissions, identity and trust operate as payment services interact with increasingly automated and AI-enabled forms of commerce. 

The design of the Digital Pound Lab

The Lab was based on the platform model of a digital pound described in the Consultation Paper, where the central bank provides the infrastructure that PIPs can access to provide services to users. ESIPs are also able to provide value-add services to users.

Although based on the platform model, the design of the Lab does not indicate the final design choices for a production digital pound. Instead, it helps test different technology and functional propositions. It also helps us assess the requirements for a platform for innovation by demonstrating which components or functionality support innovative use cases, and whether there are others that would need to be added or removed.

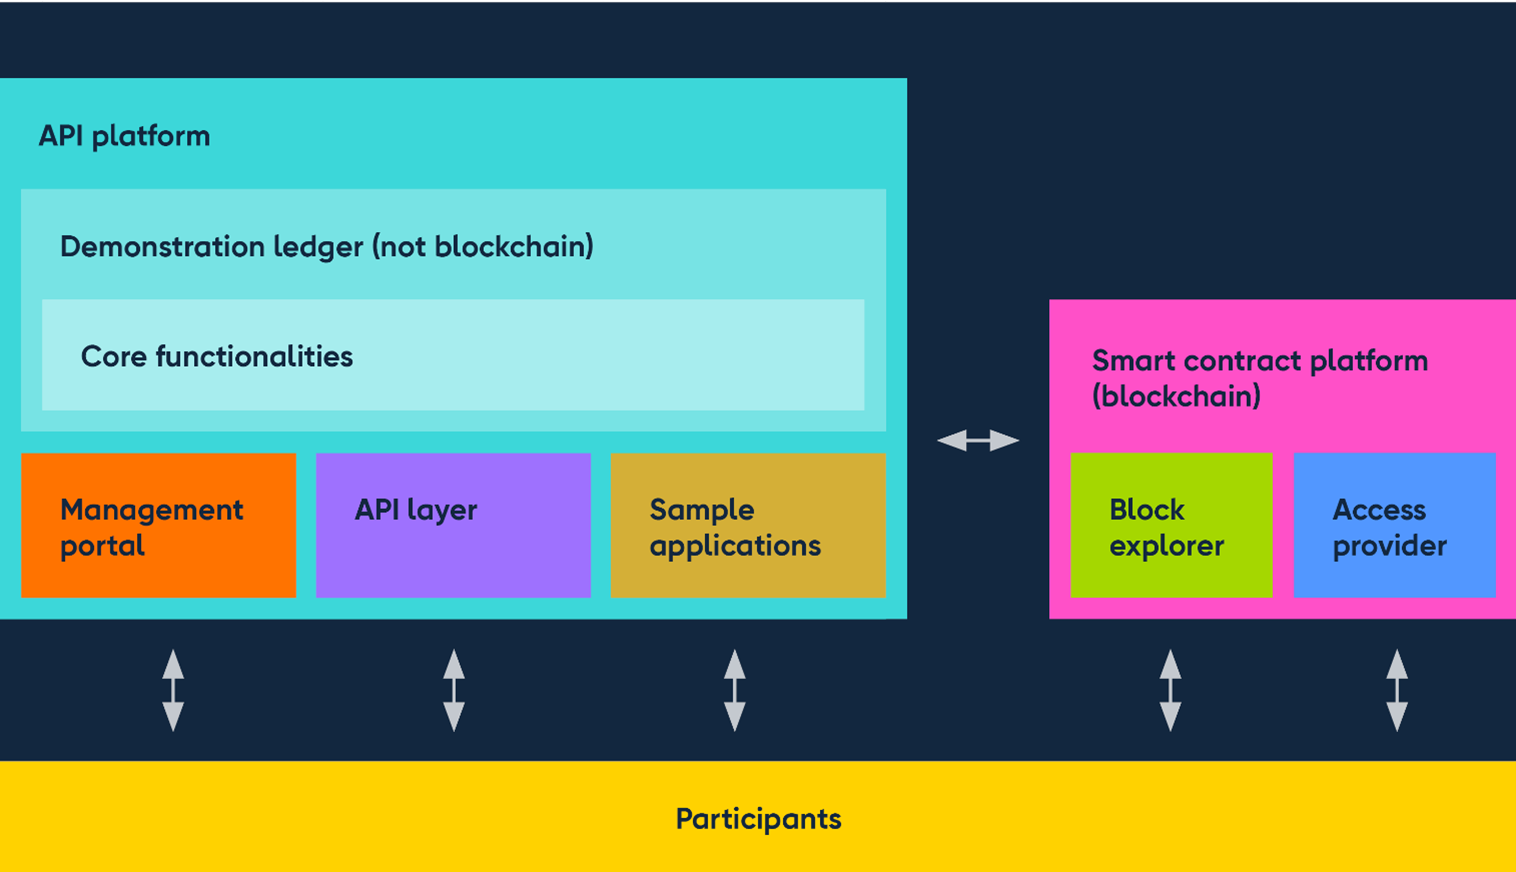
Figure 1: Diagram showing the design of the Lab

The main components of the Lab are an application programming interface (API) platform and demonstration ledger, a management portal, sample applications, and a smart contract platform, which is separate to the core functionalities.

API platform and demonstration ledger

The API platform exposes a set of APIs that allow access to the core functionalities of the Lab. Those functionalities are held on a demonstration ledger, built on a relational database management system (ie not blockchain). No decision has been made on whether distributed ledger technology (DLT) based components would form part of a digital pound design. In the Lab, we focused on testing the interoperability between centralised and DLT systems (see ‘Smart contract platform’ below).

Management portal

The management portal is where participants can check documentation, frequently asked questions, usage statistics and errors, or make feature and service requests.

Sample applications

The sample applications enable the Bank to demonstrate the capabilities of the Lab to participants and the wider industry and also helped jump-start participants to create their use cases.

The sample applications include:

  • two sample PIPs and wallet applications
  • a mock e-commerce website to demonstrate various checkout experiences
  • a chat application to demonstrate how users might connect their wallets to third-party applications while maintaining user privacy and security to make and co-ordinate payments

Participants had two routes of entry into the Lab:

  1. Creating their own PIPs and wallets
  2. Using our sample PIPs and wallets. This supported participants who were interested in building their use cases but preferred to integrate an existing wallet to avoid having to build basic functionalities, like log-in and balance display screens.

However, if there was functionality required to support a use case, that doesn’t already exist in the sample PIP and sample wallets, participants were required to build their own PIP and wallet to support their use case.

Smart contract platform

The smart contract platform communicates with the core functionalities of the Lab through the sample PIPs and enables the creation and execution of smart contracts. Participants could also connect their own PIPs to the smart contract platform if preferred. It has an access provider component which allows participants read and write access to the smart contract platform, so they do not have to host the logic themselves. 

The demonstration digital pounds in the Lab are held on the demonstration ledger, not the smart contract platform. There will be functionality that allows the swapping of items on the smart contract platform for digital pounds, helping test opportunities for interoperability between blockchain and non-blockchain systems.

The smart contract platform is built using Hyperledger Besu and provides a secure environment for participants to test interoperability of the digital pound with digital assets and programmable ledgers.

  • API Platform

    Capability

    Description

    Payments

    • omnichannel payments across points of sale, e-commerce, API-based and other emerging forms of payments
    • QR and NFC-based payment initiation
    • making requests to pay, including refunds
    • split payments

    Account management

    • opening an account
    • creating, looking up or deleting aliases
    • looking up balances (both available and total)

    Conditional payments

    • enabling users to authorise a third-party to spend up to a certain amount within a specified time frame (similar to the allowance and approval concept in an ERC20 contract)
    • enabling users to put money aside in conditional ‘locks’, including:
    • allowing the receiver to draw down funds up to a date and amount specified by the sender
    • allowing funds to be drawn down based on the decision of a third party
    • allowing funds to be transferred if a cryptographic hash is provided within a specified timeframe

    ESIP connections

    • allowing users to connect their wallets to, and make payments from, third-party applications

    Trusted credentials (optional use)

    • supporting confirmation of payee and payee authentication, including the use of digital signatures
    • allowing the authentication of users through third-party applications (or ESIPs)
    • supporting payment tokens for use in autonomous payments

    Security and privacy

    • optional privacy-preserving payments
    • enabling one-time wallet addresses and privacy-enhancing technologies

    Smart contract platform

    Capability

    Description

    Smart contract functionality

    • creating and executing smart contracts
    • atomic swap functionality items, such as digital assets, for digital pounds. The digital pounds never move off the demonstration ledger.

    Block explorer

    • the ability to view transactions that have occurred on the smart contract platform

    In addition to the features mentioned above, we may implement regular feature updates based on feedback from participants. We will keep this page updated with any new features implemented.

    • Fluxpay Limited
    • LINK in collaboration with Consult Hyperion
    • NOBO Finance in collaboration with Applied Blockchain
    • Yotra Ltd
    • CRM.COM
    • Crunchfish
    • Finoxy Labs
    • Focus on Monesave
    • LINK in collaboration with Consult Hyperion
    • Leeds City Council x Aire Logic
    • NOBO Finance Limited In collaboration with Dun & Bradstreet and Polygon
    • OneID
    • TECHT Labs
    • The Scottish Centre of Excellence in Digital Trust and DLT
    • Transpact.com
    • Yotra Ltd
    • Accenture
This page was last updated 02 October 2026